
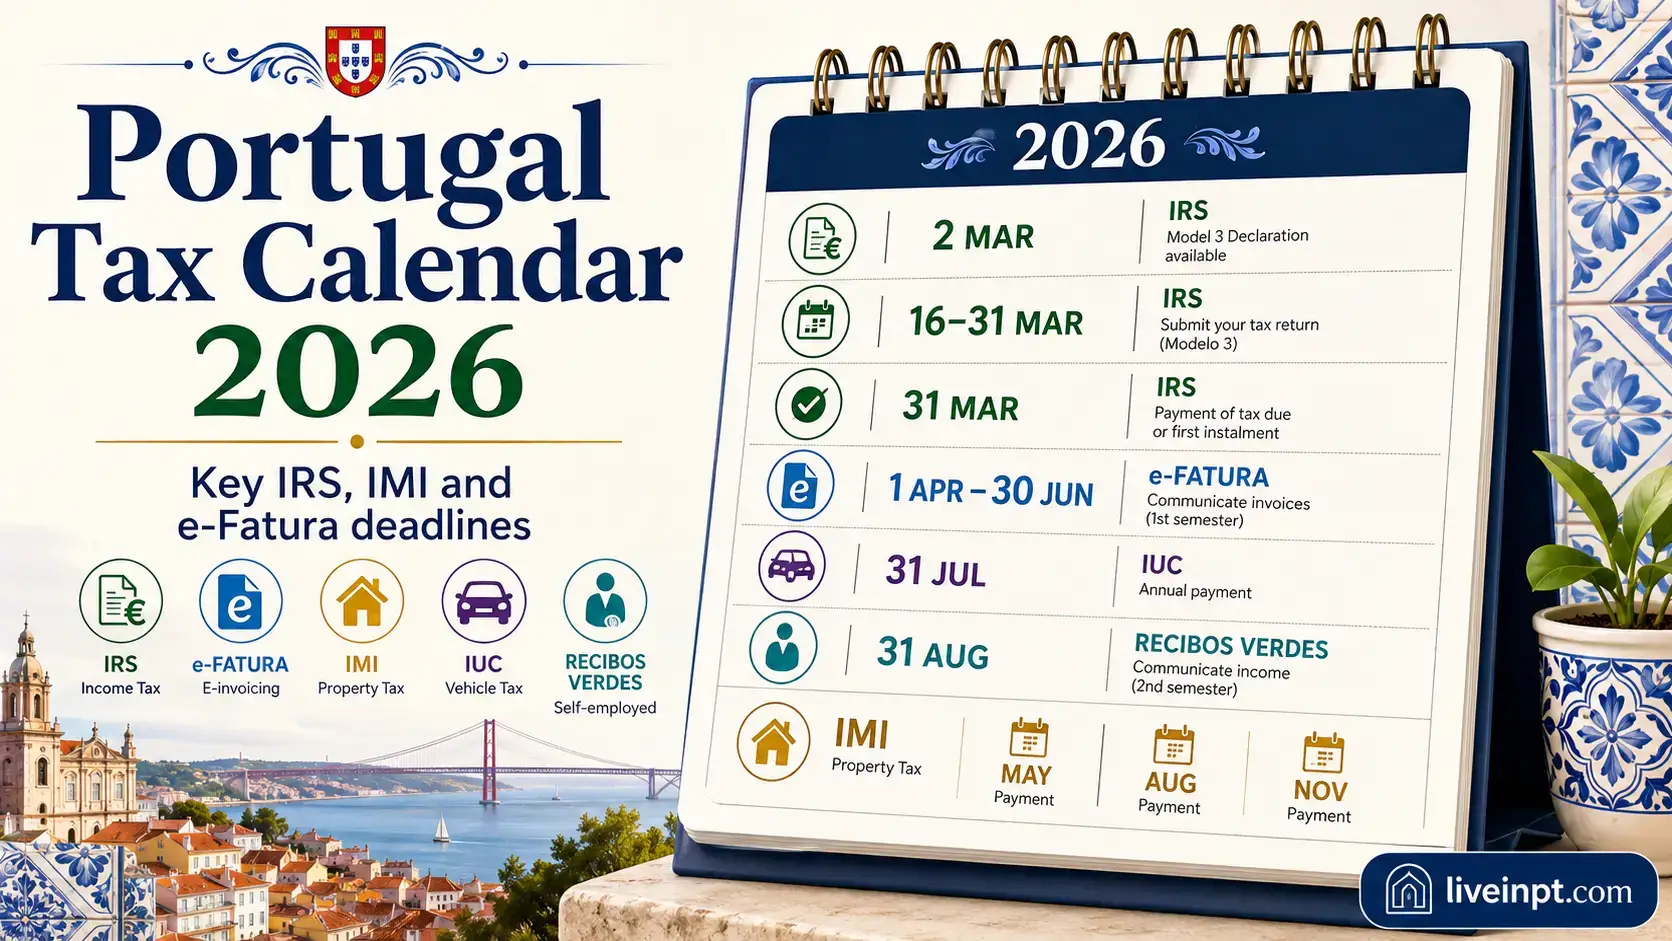
The normal Portuguese IRS filing window for 2025 income was 1 April to 30 June 2026. As of 19 November 2026, that deadline has passed, but property owners and independent workers may still have payments or declarations due before year-end.
Use the dates below to identify your next obligation, then check the document and tax year in your own account. If you never confirmed IRS Automático, check your return status before assuming nothing was filed: an eligible provisional return can become definitive automatically.
How to Use This Calendar
This is a calendar of obligations falling in 2026, not a list of deadlines every resident must meet. IRS normally concerns the previous year’s income; VAT and Social Security follow their own reporting periods. A payment on account can concern the current year’s eventual IRS bill.
Start with your situation: property owner, vehicle owner, independent worker, or taxpayer checking a 2025-income return. For an individual assessment, late return or collection notice outside the normal timetable, read its own deadline. Do not apply the annual calendar to it blindly.
2026 Tax Deadline Table for Foreign Residents
Remaining obligations checked on 19 November 2026
| Deadline | Applies when | Action |
|---|---|---|
| 20 November | Independent-worker contribution is due for October | Pay the amount shown in Segurança Social. This is separate from declaring quarterly income. |
| 20 November | Normal quarterly VAT regime, July–September 2026; or monthly VAT return due this month | Submit the periodic VAT return. Filing and payment are separate actions. |
| 25 November | VAT payment is due under the relevant normal quarterly or monthly regime | Pay the balance using its payment document. VAT exemption does not create a quarterly payment merely because you issue recibos verdes. |
| 30 November | Annual IMI exceeds €100 and a final instalment remains unpaid | Pay the November instalment shown in your collection note. |
| 30 November | Independent worker under organised accounting wants the quarterly Social Security assessment regime for 2027 | Make the optional election described below. This is not a quarterly income declaration for November. |
| 21 December | A third IRS payment on account is due for 2026 | Check the current payment document and pay the applicable instalment. |
| 21 December | A monthly VAT return is due in December | Submit that return. Quarterly filers do not have an extra return just because this date appears here. |
| 28 December | Monthly VAT payment is due in December | Pay the amount associated with that return. |
| 31 December | A valid foreign-income extension was communicated to AT within the ordinary IRS filing period | File the extended 2025-income return. See the conditions below; foreign income alone does not grant this extension. |
The tax dates come from AT’s 2026 payment calendar and declaration calendar. Social Security obligations are conditional on your registration, exemptions and notifications.
The Pre-IRS Deadlines People Miss Before April
These dates concerned the 2025-income return filed in 2026. They are closed windows, not tasks to complete again in November.
| 2026 date | What the window covered | Official route |
|---|---|---|
| 16 February | Landlords communicating qualifying long-duration residential contracts or cessation for the relevant tax treatment | Portal das Finanças: Arrendamento > Contratos Longa Duração > Comunicar Duração Contrato Longa Duração |
| 2 March | Registering or validating 2025 invoices in e-Fatura | e-Fatura > Adquirente |
| 2 March | Communicating household changes with reference to 31 December 2025 | Portal das Finanças: Dados Agregado IRS |
| 16–31 March | Reviewing deductions and complaining about eligible general-family-expense or invoice-VAT figures | IRS > Consultar despesas p/ Deduções à Coleta; complaints through Contencioso Administrativo > Instauração de Contencioso sobre Deduções à Coleta |
| 31 March | Optional advance choice of an organisation for IRS/IVA consignação | Dados Agregado IRS > Comunicar Entidade a Consignar IRS/IVA |
Household composition affects matters such as dependants and joint filing. AT’s automatic return uses the household information communicated for the relevant year, then prior information or its fallback where necessary.
The March consignação date was an advance selection deadline. It was also possible to choose an eligible beneficiary in Quadro 11 of the Modelo 3 cover sheet, or before confirming IRS Automático. It was not a blanket last chance to make the choice. AT explains the two routes in its consignação guidance.
Missed e-Fatura validation does not mean every expense can simply be added to Anexo H. AT provides a specific correction route in Quadro 6C for eligible health, education, housing, care-home and domestic-work expenses. If you reject AT’s communicated values there, enter all the relevant household expenses by holder, including unchanged amounts, and retain the supporting documents. General family expenses and invoice-VAT deductions use a different complaint route. See the e-Fatura guide for invoice classification; for a correction after the filing season, use the late-action section below.
IRS Filing Season: 1 April to 30 June 2026
April was the opening of the ordinary filing period, not its deadline. Filing on the first day was not compulsory, and waiting a fixed number of days was not an official requirement. The useful check was whether income, household details, deductions and annexes were complete.
For a return you must submit manually, sign in to Portal das Finanças, choose IRS > Entregar Declaração, and select income year 2025. Save the submission receipt and check that the return is accepted rather than left with validation errors.
Foreign income does not itself remove a Portuguese filing obligation. Tax residence, the income received and any filing exemption determine the answer. The IRS guide for foreigners covers residency, Anexo J, other annexes and replacement returns. This calendar does not replace that analysis with a rule that every resident must file.
IRS Automático: check what happened to the return
AT’s IRS Automático guidance says that, for an eligible taxpayer not exempt from filing, an unconfirmed provisional return becomes definitive after the filing deadline if no Modelo 3 was submitted. Not pressing “confirm” does not necessarily mean non-filing.
Use IRS > IRS Automático to review the information, and AT’s Consultar Declaração service to establish what was filed. Nationality is not the eligibility test. Some qualifying service providers can use the automatic route; foreign income, partial-year residence or information missing from the draft require particular care.
For the specific automatic-conversion situation, AT allows a replacement return without penalty within 30 days following the assessment. That clock runs from the assessment, not from when you read this page. For an incorrect automatic return, AT directs taxpayers to Modelo 3 with Declaração de Substituição marked in Quadro 10 of the cover sheet. If the applicable correction period has passed or the portal blocks the change, use e-balcão with the assessment and return receipt.
Foreign-income extension: a conditional year-end deadline
The AT foreign-income FAQ allows an extension where qualifying foreign income gives a right to an international double-tax credit and the foreign final tax was not determined by the ordinary filing deadline. The taxpayer had to communicate the qualifying circumstances within that filing period through Modelo 49, identifying the income and source country.
If you used that route, retain the Modelo 49 receipt and foreign assessment evidence when preparing the extended return. A foreign filing extension or a late foreign tax document, by itself, does not show that the Portuguese communication requirement was met.
After You File: Refunds, Nota de Liquidação, and Payment Deadlines
AT’s ordinary timetable for returns filed on time points to 31 August 2026 for the refund or payment stage. That is not a promise that every delayed, corrected or late-filed case is settled by that date. Check the assessment and current payment document for your case.
The nota de liquidação is the assessment, not your submission receipt. Compare the income, deductions, withholding and final balance with your records. Use Consultar Declaração to establish return status, and A Minha Área > Pagamento > Pagamentos a decorrer for current amounts payable. Keep both the assessment and proof of any payment.
IBAN before filing
Use Serviços > Dados Cadastrais > Alteração de Dados Cadastrais > IBAN > Alterar IBAN, or search “alterar IBAN” within the portal. AT considers the registered account valid after the bank confirms ownership, with status Confirmado.
An IRS Modelo 3 return can also specify a different account for that IRS refund. Compare both records when tracing a missing reimbursement. AT explains the distinction in its bank-details guidance. A refund IBAN and an authorisation to debit tax payments are separate things.
Deadlines That Depend on Your Situation
IMI months and checking your payment reference
For ordinary annual IMI relating to 2025 and paid in 2026, the schedule is:
| Total annual IMI | Ordinary 2026 instalment deadlines |
|---|---|
| Up to and including €100 | 1 June |
| More than €100, up to and including €500 | 1 June and 30 November |
| More than €500 | 1 June, 31 August and 30 November |
The normal first-payment month is May; 31 May 2026 was a Sunday, so AT’s calendar moves that deadline to 1 June. Exactly €100 belongs in the one-payment band, and exactly €500 in the two-payment band. If you already paid the whole annual amount, do not pay a later instalment again.
Sign in and open Imposto Municipal sobre Imóveis > Consultar Notas de Cobrança. Select the relevant tax year and download the collection note. AT’s annual property-tax guidance explains the schedule. An assessment issued outside the ordinary annual cycle can have another deadline.
AIMI, where assessed, had a separate 30 September 2026 payment deadline. The IMI and AIMI guide owns the rates, exemptions, taxable values and ownership rules.
IUC: use the vehicle’s own payment period
Under the ordinary 2026 annual rule, IUC falls in the vehicle’s registration month, with the applicable working-day adjustment. In Portal das Finanças, use IUC > Entregar Ano Corrente, select the vehicle category and search for the registration. Select the vehicle, choose Emitir, check the details and select Emitir para Pagamento to obtain the document. AT shows this sequence in its IUC payment leaflet.
First registration and imported-vehicle cases need their specific deadline, so do not calculate one from your arrival in Portugal. If the vehicle or period shown is unexpected, ask AT through the channel below with its registration and document details.
Recibos verdes: keep three calendars separate
Issuing recibos verdes does not settle annual IRS, periodic VAT or Social Security. Check which obligations apply to your registered activity.
VAT: For an applicable periodic return, use IVA > Declaração Periódica > Entregar Declaração in Portal das Finanças; the official service menu also lists Obter comprovativo and Obter documento de pagamento. Retain its receipt and the associated payment document. The return deadline and the tax-payment deadline differ; submitting one is not proof of doing the other.
Social Security: Independent-worker contributions are paid monthly between the 10th and 20th of the following month. The income declaration is normally quarterly, covering the three preceding months. In 2026 its ordinary deadlines were 2 February, 30 April, 31 July and 2 November, including the weekend adjustments in the official FAQ. For example, the October declaration covered July–September income; it did not replace the separate monthly payments.
Use Trabalho > Remunerações e contribuições > Trabalhadores Independentes > Entregar declaração trimestral in the Segurança Social portal. For payment records, exemptions and contribution calculations, follow the independent-worker contributions guide. The employer contribution deadline is a separate rule; do not apply it to your own independent-worker payment.
Organised accounting: The official 6 November notice describes the optional election for quarterly assessment in 2027. Its route is Trabalho > Remunerações e contribuições > Trabalhadores independentes > Alterar opção de contabilidade organizada para declaração trimestral. Read your notification before making the choice.
If you arrived in Portugal mid-year
Establish the tax-residency period before deciding which income belongs in the return. An immigration permit date and a Portuguese tax-residency period are not interchangeable. If another country also requires a return, its deadline does not automatically extend Portugal’s. Keep arrival/residence evidence and foreign income and tax statements with your filing records.
Common Mistakes
Check the tax year before paying a second demand. A final IRS balance for 2025 and an IRS payment on account for 2026 are different obligations. The latter is an advance towards the eventual 2026-income assessment.
AT’s 2026 calendar scheduled payments on account for 20 July, 21 September and 21 December. They apply where due; do not assume every independent worker owes an identical instalment. CIRS Article 102 governs calculation and circumstances for reduction or cessation. Before reducing one, establish the basis with your accountant rather than treating a forum example as permission.
For each payment, compare the tax, year, instalment, document number, amount and deadline. Use the reference on that document and retain the payment confirmation. If a debt still appears after a payment, send AT both records so it can trace the allocation.
Do not assume a newly created direct-debit authorisation covers an imminent bill. AT’s direct-debit FAQ tells taxpayers to check the authorisation’s effective date and use another authorised payment method when necessary. Changing a refund IBAN does not itself set up collection of your taxes.
Late Filing, Coimas, and What to Do If You Miss a Deadline
First distinguish a missing return, an incorrect return and unpaid tax. They need different fixes.
| What you find | Next action | Evidence to retain |
|---|---|---|
| A required IRS return is absent, after checking automatic conversion | Submit the correct-year Modelo 3; if blocked, send AT the exact error through e-balcão | Return receipt, income statements and error screenshot |
| A filed return has wrong or missing information | Establish the appropriate replacement/correction route for that return and assessment date | Filed return, assessment, invoices or foreign-tax evidence supporting the change |
| Tax is unpaid or the reference is expired | Check the current payment record; ask AT for the applicable payment document if none is available | Assessment, original notice and any payment attempt |
| Payment was made but the debt remains | Ask AT to trace the payment against the specific demand | Bank/payment confirmation and the demand’s reference |
| A deduction or household error is unresolved | Identify the exact affected field and ask which correction route remains available | Original return and the documents proving the correct information |
Late filing can lead to a coima, and overdue tax can create interest and collection consequences. The amount and available correction or reduction procedure depend on the case; there is no single fine this calendar can quote for every reader.
For a written, traceable question, follow AT’s e-balcão instructions: sign in, open Todos os Serviços > Contactos > Atendimento e-balcão > Registar nova questão, select the relevant tax/area and question type, describe the issue and attach the supporting records. Include the income or tax year and assessment/document number. Keep the registration confirmation and return to the registered interaction for replies.
A question to AT does not, by itself, give you a new filing or payment deadline. If you received a formal notice, use the deadline and procedure on that notice.